

Contactless Payments & Payment Optimization
Contactless Payment Solutions: Why Growing Businesses Choose CPP
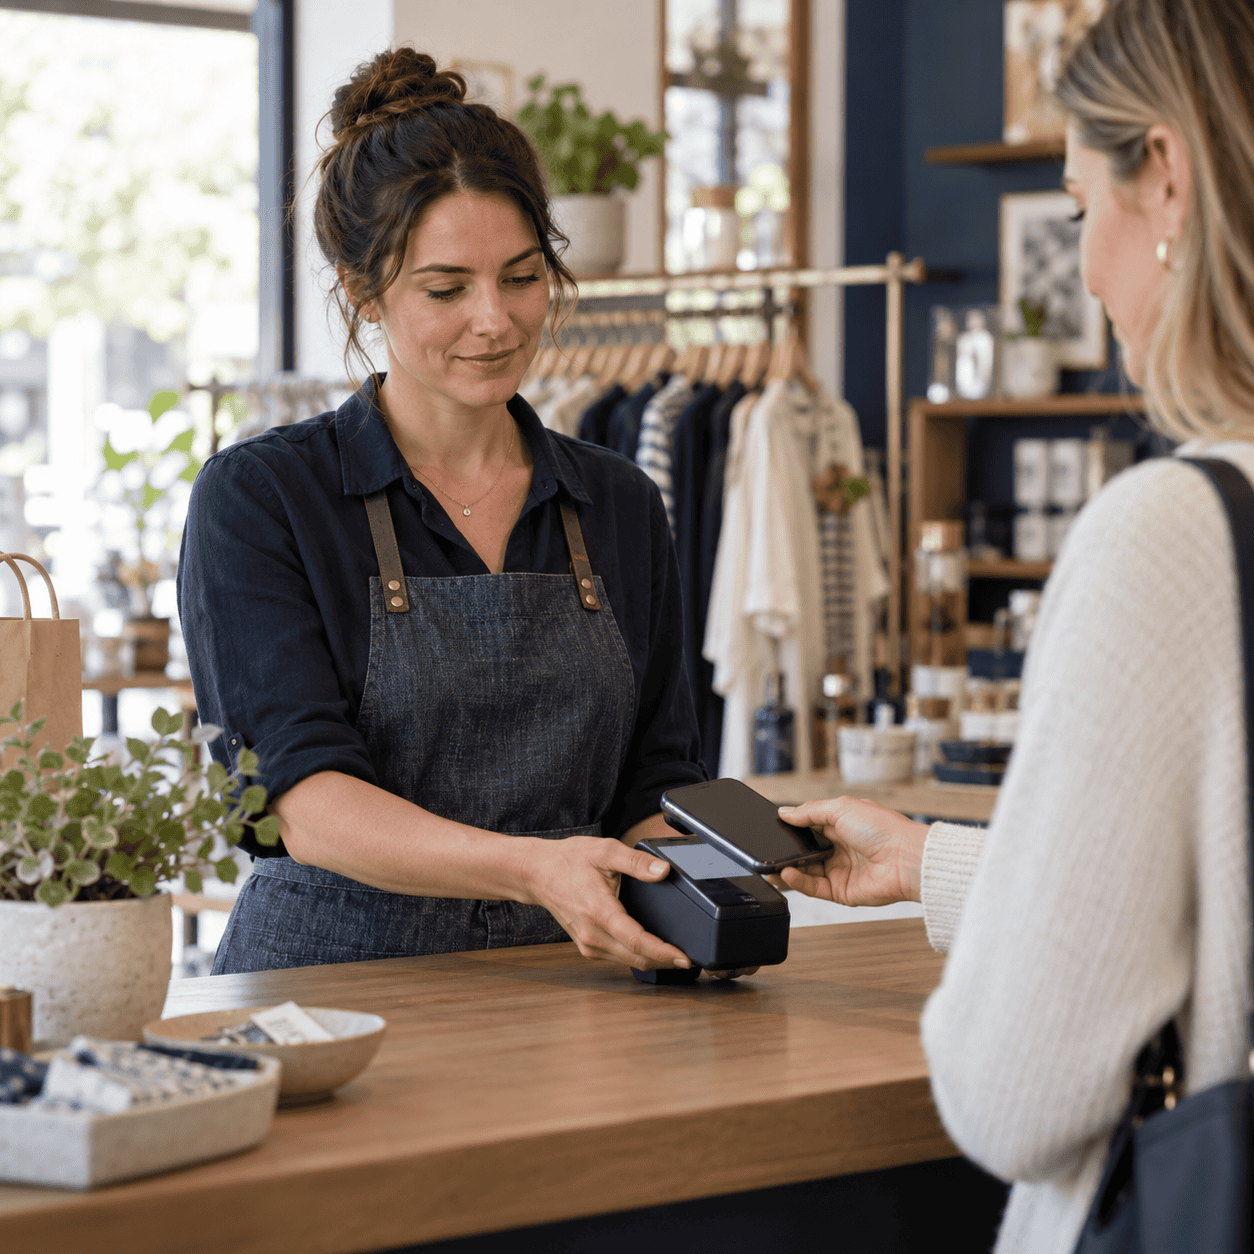
Your customer taps a card or phone. The payment is approved. Everyone moves on.
That is the visible part of accepting payments.
The less visible part includes processing charges, gateway fees, billing settings, declined transactions, and the time your staff spends matching payments to invoices.
Square, PayPal, and other payment providers may already give you a way to collect money. The reason to consider Contactless Payment Processing (CPP) is what happens around that transaction.
CPP is a payment optimization consultancy that also provides processing and payment tools. We help business owners evaluate their costs, identify operational problems, and choose a setup that fits how they actually get paid.
For a growing business, the question goes beyond “Can we accept contactless payments?” It becomes “Is our payment setup serving the business as well as it could?”
What Contactless Payments Actually Do
Contactless payments let customers use a compatible card or NFC-enabled device at a compatible terminal without inserting the card. NFC stands for near-field communication.
This can make the payment step quicker and more convenient. EMV contactless transactions also use a transaction-specific security code to help protect against counterfeit fraud.
Those benefits matter. They are also features of the payment technology, rather than a reason to choose one consultant or provider over another.
A terminal that accepts a tap does not automatically tell you whether your monthly fees make sense. It does not decide how to collect outstanding balances or whether staff are creating unnecessary work by entering the same information twice.
That is where the choice of payment partner starts to matter.
Why Consider CPP If You Already Use Square or PayPal?
If your current platform meets your needs at an acceptable total cost, familiarity has value. Changing providers should have a business reason.
CPP gives you a way to evaluate that reason.
Perhaps your business started with occasional payments and now collects substantial monthly volume. Perhaps you added invoices, deposits, recurring billing, or a second location. The system that suited the original business deserves another look when those needs change.
The relevant comparison is the complete arrangement: pricing, payment tools, staff workflow, reporting, and the effort involved in making a change.
Working with CPP means bringing those questions into one review. We can assess processing costs and payment workflows together, then help implement an appropriate solution when the findings support it.
The value is an informed recommendation tied to your business. A recognizable payment brand alone cannot answer whether your particular configuration is the right fit.
Look at the Full Cost of Getting Paid
Business owners often compare providers using an advertised percentage. That is an understandable starting point, although it can leave out meaningful expenses.
A useful comparison includes percentage charges, per-transaction fees, monthly charges, gateway costs, software costs, and equipment expenses that apply to the proposed setup.
Transaction size matters, too.
For illustration, a hypothetical $0.20 transaction fee equals 2% of a $10 sale. The same fee equals 0.02% of a $1,000 sale. These figures are an arithmetic example, not a CPP quote or a competitor's pricing.
That is why two businesses with similar monthly volume can need different payment strategies.
The way payments are collected also matters. A business handling in-person payments, online invoices, and recurring charges should compare the costs of those actual channels.
CPP's approach begins with the business's activity and statements. The goal is to understand the expense before recommending a change.
Savings Can Come From the Workflow
Imagine a service business that collects deposits online and final balances when customers arrive.
If staff routinely enter card details manually even when a customer is present, CPP would examine why. The answer might involve equipment placement, disconnected systems, training, or an established habit.
A compatible card-present workflow may be worth evaluating. Its financial benefit depends on the pricing arrangement and transaction characteristics.
Consider a second business that takes payments by phone. Staff spend time answering calls, entering details, and finding the right invoice afterward.
A hosted payment page could let customers submit their own payments. Whether it helps depends on how invoice references, customer records, and payment confirmations are handled.
Buying a tool is only part of the solution. Designing the process around the tool is what makes it useful.
CPP reviews those practical details because a payment system should help your team complete the job with less confusion.
Gateway Settings Deserve Attention
A gateway connects payment tools to processing services. Its configuration can affect how transactions are screened and how customers experience payment collection.
For example, an address verification rule or transaction limit may deserve review when legitimate payments are repeatedly blocked. Loosening every control is not a sound response, either.
The relevant questions include what the system is detecting, which transactions are affected, and how the controls fit the business's risk and payment patterns.
CPP can evaluate gateway and AVS settings as part of the wider payment workflow. AVS is the address verification service used in certain card payment flows.
Security decisions should be based on evidence. A change intended to reduce friction should also account for fraud exposure.
This is one reason a business may benefit from payment consulting even when its terminal appears to be working perfectly.
Contactless at the Counter, Better Collection Everywhere Else
Many businesses collect money in more than one place.
A customer might pay a deposit online, settle a balance in person, and later authorize recurring payments. Each step needs an appropriate process.
A good review asks whether staff can connect those payments to the correct customer and invoice without unnecessary manual work.
CPP considers contactless devices alongside hosted payment pages, invoice collection, and recurring billing support. Available capabilities and integrations depend on the platforms selected.
For recurring payments, practical questions include how authorization is captured, how payment credentials are stored through supported tools, and how staff handle unsuccessful charges.
For invoice payments, the questions include whether the customer understands the amount due and whether the payment can be reconciled correctly.
The terminal is one part of that system. The business needs the whole collection process to make sense.
How CPP Evaluates This
A useful recommendation starts with how your business operates. CPP's review can include the following areas.
1. Customer payment behavior
How do customers prefer to pay? How much activity happens in person, online, by phone, or through repeat billing? The answer helps determine which tools deserve attention.
2. Average transaction size and payment mix
Small purchases, larger invoices, and recurring charges create different cost considerations. Debit volume and other payment characteristics also help inform the comparison.
3. Current processing expenses
Recent statements provide a basis for reviewing fees and comparing alternatives. A percentage quoted without context does not show the full monthly cost.
4. Gateway configuration and payment controls
CPP examines relevant settings, verification rules, and transaction patterns to understand where avoidable friction may occur.
5. Invoice and recurring billing workflows
The review considers how staff collect deposits, balances, and repeat payments, including what happens when a payment fails or needs follow-up.
6. Reporting and reconciliation
A payment approval should be usable by the people maintaining your records. CPP considers how payments are matched to the business's operational needs.
7. Implementation requirements
A proposed change should account for equipment, software compatibility, staff training, contract terms, and any migration questions. Moving recurring payment data, for example, requires verification rather than an assumption.
8. Customer communication
Changes should be understandable to customers. A technically functional setup can still create problems if amounts, instructions, or payment options are unclear.
The result should be a recommendation you can evaluate: the problem, the proposed change, the expected benefit, and the conditions that could affect that benefit.
You can read more about this approach on CPP's payment optimization page.
Surcharging Is a Separate Decision
A business looking to reduce processing expenses may ask about passing eligible card costs to customers.
That deserves its own evaluation. A surcharge can introduce customer friction, and enabling one requires attention to applicable rules, payment methods, disclosures, and platform capabilities.
Rules vary. Verify current requirements and complete a compliance review before implementation.
CPP considers the financial and customer experience questions together. A business may have other opportunities worth reviewing before adding a customer-facing fee.
For background, see CPP's Credit Card Surcharge Laws by State guide and Zero Cost Credit Card Processing resource.
A contactless upgrade and a surcharge program are separate decisions. One does not require the other.
When a CPP Review Makes Business Sense
A payment review becomes especially useful when the current setup leaves you with unanswered questions.
Your processing expenses may be difficult to explain. Your team may be spending too much time chasing payments or matching them to invoices. You may have added locations, recurring billing, or a new payment channel without reviewing how the pieces fit together.
Repeated payment problems are another reason to look closer. A series of legitimate declines deserves investigation rather than an endless cycle of staff workarounds.
You might also be considering a proposal from another provider. Before switching, it helps to understand whether the offer addresses the actual source of cost or friction.
CPP is a fit for businesses that want that level of evaluation and, where appropriate, help putting the resulting strategy into practice.
The reason to choose us is the combination of payment analysis, workflow consulting, and implementation support around your business's needs.
What to Compare Before Making a Change
Ask any prospective payment partner to explain the total expected cost using your transaction volume, average ticket, and payment channels.
Ask which tools and services are included, which cost extra, and what assumptions the proposal makes.
If integration is part of the recommendation, verify the specific connection your business needs. “Integrates with your software” should lead to a practical explanation of what information moves, when it moves, and what staff still need to do.
Also ask about the transition. Existing agreements, equipment compatibility, recurring payment credentials, and reconciliation procedures can all affect the effort involved.
These questions help turn a sales conversation into a decision you can defend.
CPP's consultative approach puts those business considerations at the center of the review.
Choose a Payment Partner Around Your Business
Contactless payments can improve the customer experience at the counter. Choosing the right payment partner can improve how your business collects, manages, and understands its money.
The reason to consider CPP is the work behind the recommendation: reviewing your expenses, examining your workflows, and evaluating changes against your actual needs.
You should be able to explain why a proposed setup makes sense for your business before committing to it.
Take the $500 Challenge
Wondering whether your current payment setup is costing more than it should?
CPP reviews two recent merchant statements for savings opportunities. If the review identifies none, CPP pays you $500, subject to the Challenge's eligibility requirements.
The Challenge is designed for established businesses already processing approximately $50,000 or more per month. Businesses using surcharge, cash discount, dual pricing, or net-zero-cost models may not qualify.
Start with your statements and get a clearer picture of your costs.
Frequently Asked Questions
Why consider CPP if I already use Square or PayPal?
Consider CPP when you want a review of your processing expenses and payment workflows. The decision should be based on your actual costs, operational needs, and the expected benefit of any proposed change.
Does accepting contactless payments automatically lower my processing costs?
No. Contactless describes how a payment is accepted. Your total cost also depends on your pricing agreement, transaction characteristics, and applicable fees.
Does CPP provide payment tools as well as consulting?
Yes. CPP provides payment consulting and can support processing, gateway strategy, hosted payment pages, recurring billing, and contactless device options where appropriate.
Will changing providers require changing all of my software?
That depends on the existing systems and proposed solution. Compatibility, integration requirements, and migration steps should be verified before a change.
Do I have to add a surcharge to work with CPP?
No. CPP evaluates payment optimization opportunities based on your needs. Surcharging is a separate strategy that requires financial, customer experience, and compliance review.
What should I prepare for the $500 Challenge?
Prepare two recent merchant statements and information about how your business accepts payments. Review the Challenge page for eligibility requirements before submitting.